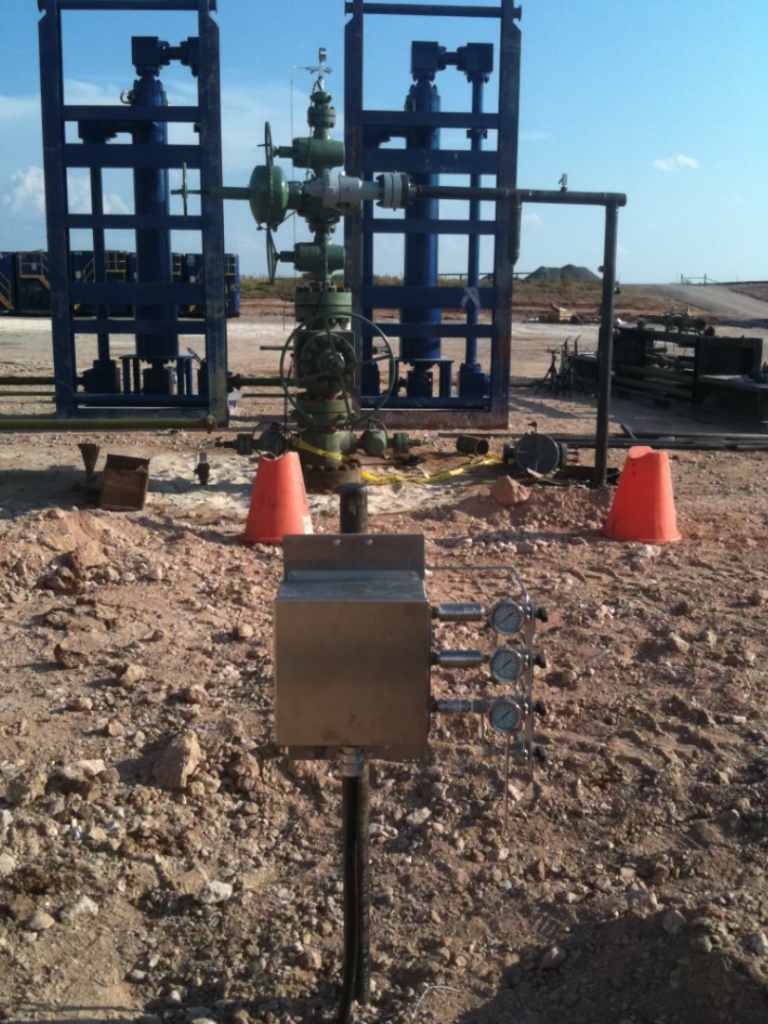
Tuesday, April 20, 2021

Publicity agent?

Originally published by David Coale.

In Snell v. Ellis, the Fifth Court noted – but did not resolve – the issue whether an agent’s speech on behalf of a principal can implicate the TCPA. It did observe, however, that: “The plain text of section 27.005(b), long-standing rules regarding agency, and our decisions in other contexts suggest the answer is ‘no’ ….” No. 05-20-00642-CV (April 5, 2021) (mem. op.)

The post Publicity agent? appeared first on 600 Commerce.

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/3n5fyTf
via Abogado Aly Website

Lawyers: Spend a Day with Your Clients with No Charge

Originally published by Cordell Parvin.

When it is considered safe to visit, I recommend you spend a day with your clients with no charge. This is especially important if COVID has kept you from seeing clients in person.

I did that frequently as a lawyer and even put associates in my clients’ offices or out on a construction project and did not charge for their time. I remember at least two of my visits were to bridge construction projects like the one pictured here.

I thought of this recently when Nancy and I went to Best Buy to buy a new dishwasher. After deciding on the one we wanted we began speaking with Jacob, our young salesperson about making our home smarter. After a few minutes our young sales representative gave us a brochure for a free home consultation.

A couple of days later our home consultant spent at least an hour helping us figure out options for making our home smarter. It was time well spent and I believe brilliant marketing by Best Buy.

When I was coaching I shared the give away a day idea with many of the lawyers I coached. Each one who did it found it valuable and many came back to the office with one or more new projects.

The post Lawyers: Spend a Day with Your Clients with No Charge appeared first on Cordell Parvin Blog.

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/3sz2SoM
via Abogado Aly Website

Monday, April 19, 2021

Texas Supreme Court Addresses Postproduction Costs

Originally published by Tiffany Dowell.


A recent Texas Supreme Court case, BlueStone Natural Resources II, LLC v. Randle, addressed a dispute over postproduction cost allocation for royalties.  I thought this Opinion offered a good explanation of postproduction costs generally, and comparison of the two clauses at issue in the leases, which made it worth taking a look at on this blog.  [Read Opinion here.]

Background

In 2003, several mineral owners (“lessors”) executed oil and gas leases with Quicksilver Resources.  Each of the leases contain a 2-page Printed Lease and an attached Addendum.  The Addendum states that its language “supersedes any provisions to the contrary in the Printed Lease.”  The two documents differ in their language with regard to royalty calculation under the lease.

The Printed Lease requires that royalties be paid on the “market value at the well…or the gas so sold or used off the premises.”  It requires royalties to be “computed at the mouth of the well.”  The Addendum provides that “the lessee agrees to computer and pay royalties on the gross value received, including any reimbursements for severance taxes and production related costs.”  The Addendum also includes what the Court referred to as “typical no deductions language” providing that “royalties accruing under this lease shall be without deduction for postproduction costs.  Not surprisingly, this inconsistency led to a dispute over whether royalties under the lease should be paid on the gross value received or the value received less postproduction costs.

The Printed Lease also requires payment for gas “sold or used off the premises or for the extraction of gasoline or other product therefrom,” subject to the following exception: “Lessee shall have free from royalty or other payment the use of…gas…produced from said land in all operations which Lessee may conduct hereunder, including water injections and secondary recovery operations, and the royalty on…gas…shall be computed after deducting any so used.”

Dispute

For over 10 years, Quicksilver paid gas royalties on the gross value received, without deducting postproduction costs.  When BlueStone Natural Resources II, LLC acquired the lease from Quicksilver in 2016, it began deducting post production costs pursuant to the language in the Printed Lease.  Royalty payments dramatically declined, and four groups of mineral owners sued BlueStone.  The suits were consolidated and the lessors claimed that BlueStone was improperly deducting post production costs because the lease–due to the Addendum–unambiguously requires royalties to be calculated on “gross” receipts “without deductions.”  BlueStone agrees that “gross value received” in the Addendum supersedes the Printed Lease’s “market value” royalty language, but they argue that the Printed Lease mention of “at the mouth of the well” is the only lease language providing a valuation point, so nothing in the Addendum is contradictory of that portion of the Printed Lease such that it would supersede.


While this litigation was pending, the lessors discovered that BlueStone was not paying any royalties on commingled gas that was used as plant fuel by a third-party processor or on volumes the processor returns to BlueStone to fuel compressors both on and off the leased premises. BlueStone claims contractual right to “free use” of gas regardless of whether it is consumed on or off the lease, so long as the use benefits or furthers the leasehold operations.

Lower Court Rulings

The trial court found for the lessors on both issues on summary judgment motions.  The judge ruled that Bluestone breached the lease by deducting postproduction costs and by failing to pay royalties on both the processor and compressor fuel.

The Ft. Worth Court of Appeals affirmed, holding that the Printed Lease “at the mouth of the well” language is contrary to the Addendum’s “gross value received” language.  Given the Addendum’s language regarding any conflict, the “gross value received” language controlled.  Additionally, the court of appeals found that the free use clause did not apply to off-site uses for plant or compressor fuel.

BlueStone sought review from the Texas Supreme Court.

Opinion

The Court framed the question as whether there is a conflict between the “market value at the mouth of the well” language in the Printed Lease and the “gross value received…without deduction” language in the Addendum.  The parties agree if there is a conflict, it is the Addendum language that will control.

Primer on Production and Post Production Costs 

The Court offered a good explanation of the difference between production and post production costs at the outset of the Opinion.  Production is the process of bringing minerals to the surface.  Production for raw gas occurs at the wellhead.  A royalty is the lessor’s fractional share of production, and, depending on the lease terms, may be calculated at the wellhead, or at any downstream point. Gas royalties are generally free of production costs (those required to extract the raw gas from the land), but bears the post production costs (those incurred to prepare the raw gas for downstream sale).  This general rule is subject to modification by the parties in an oil and gas lease.

Primer on Royalty Clauses 

The Court offered a three-part construct of most royalty clauses: (i) the royalty fraction (i.e. 1/4, 1/8, etc.); (ii) the yard stick (market value, proceeds, price, etc.); and (iii) the location for measuring the yardstick (at the well, at the point of sale, etc).

BlueStone essentially argues that there is no conflict on the third point–the valuation point–because the Printed Lease states it will be “at the mouth of the well” and there is no alternate valuation in the Addendum.  The lessors claim that “gross value received” essentially encompasses both parts (ii) and (iii), with received referring to proceeds obtained at the point of sale under part (iii) and “gross” meaning without deduction under part (ii).

Primer on Royalty Clauses and Post Production Costs

The Court then offered a breakdown of the two valuation methods at issue in this case.

“Market value” means “the price a willing buyer under no compulsion to buy will pay to a willing seller under no compulsion to sell.”  This is not necessarily the contract price at which gas is sold, as leases may account for market fluctuations by setting a floor or ceiling to address differences in market value and contract prices.  The preferred method of calculating “market value” is to use actual sales comparable in time, quality, quantity, and availability of market outlets.  If this data is not available, the “net-back” method is used to estimate the wellhead value by using the proceeds of a downstream sale and subtracting postproduction costs encounter between the wellhead and the sale. Mineral leases requiring royalty calculation “at the well” mean the lessor bears its share of postproduction costs.   The formula in the Printed Lease falls into this category.

“Proceeds” clauses require measurement of the royalty based on the amount the lessee actually receives for the gas under its sales contract, regardless of whether that amount is more or less than market value.  “Proceeds” may either be the gross amount received, or the net amount remaining after deductions.  Generally, a royalty clause based solely on the price actually received is “sufficient in itself to excuse the lessors from bearing post production costs.”  However, if the clause contains modifiers, that may affect whether the lessor bears the postproduction costs.   For example, if the valuation is modified by the term “net,” it does not relieve the lessor from bearing postproduction costs.  Similarly, if modified by an “at the well” valuation point, such costs are likewise deductible. If proceeds are valued as “gross,” however, then the valuation point is necessarily the point of sale and the lessor is not subject to sharing in postproduction costs.  The Addendum language falls into this category.

Analysis

Looking at the conflicting royalty calculation issue the Court sided with the lessors, finding that the two terms do conflict.  The terms “gross proceeds” and “at the well” inherently conflict because “at the well” is a net proceeds calculation.  Because the Addendum expressly requires conflicts be resolved in favor of the Addendum language, it is the “gross value received” language that governs.  Therefore, BlueStone wrongfully deducted postproduction costs from the royalties due to the lessors.

Turning next to the plant and compressor fuel issue, the Court again sided with the lessors.  The plain meaning of the language allows on-lease uses, but is not reasonably construed as extending to off-lease uses.   Thus, the language does not allow for free use of gas off the lease premises.   The Court remanded the case for further litigation on the unresolved factual issues surrounding the amount and measure of compressor fuel damages.

Why We Care?

The main reason I wanted to write a blog post on this case was that I think the Texas Supreme Court Opinion did a good job breaking down complex royalty calculation issues and walking the reader though some of the important considerations.  Additionally, this case serves as a good reminder the difference that even a couple of words can make when determining how royalties will be calculated.  Because of this, I always recommend mineral owners use an attorney to help negotiate and draft an oil and gas lease.

Further, the issue of postproduction costs is a frequently litigated issue of which all mineral owners should be aware.  If you are interested in this topic, we have a great podcast episode with Texas oil and gas lawyer, John McFarland, focused solely on royalty calculation issues.  [Listen here.]


The post Texas Supreme Court Addresses Postproduction Costs appeared first on Texas Agriculture Law.

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/3txwNip
via Abogado Aly Website

Going to Appeals – Preparing the Protest

Originally published by Larry Jones.

Overview of the Appeals Process

The goal of the Appeals Office is to settle as many cases as possible within the broad guidelines of its Mission Statement:

The Appeals mission is to resolve tax controversies, without litigation, on a basis which is fair and impartial to both the Government and the taxpayer and in a manner that will enhance voluntary compliance and public confidence in the integrity and efficiency of the Service.

Even though much of the work of Appeals comes from examinations, its jurisdiction has expanded over the last few years.  In examination cases, the taxpayer receives the 30-day letter.  This letter is accompanied by the Revenue Agent Report and gives the taxpayer 30 days to request an Appeals conference.  In most cases, the taxpayer is required to file a protest describing the taxpayer’s position.  If the taxpayer does not request an Appeals conference, then the IRS will send the taxpayer a notice of deficiency.  If the taxpayer files a petition with the Tax Court, and has not had an Appeals conference, the IRS will send the case to Appeals to investigate a possible settlement.  In other types of cases, the IRS will send the taxpayer a letter advising the taxpayer of his right to an Appeals and giving the taxpayer a time limit in which to request an Appeals conference. You file the protest as stated in the letter from the IRS and within the 30-day period.


The Need for a Protest

The taxpayer must request in writing an Appeals conference with respect to an audit.  The dollar limitation for requiring a formal protest has increased.  If the total amount for any tax period (including tax and penalties) is more than $25,000, the taxpayer must submit a written protest to obtain Appeals consideration.  If the total amount for any tax period is $25,000 or less, the taxpayer can request an appeal by making a Small Case Request.  A taxpayer can make such a request for Appeals consideration by writing the IRS, indicating the disputed issues and the taxpayer’s reason for not agreeing.

Special appeal procedures may be provided for cases such as appeals of liens, levies, seizures, or installment agreements.  The IRS provides an appeal request form for these types of cases.  See Publication 1660, Collection Appeal Rights.  The taxpayer must submit a written protest to obtain consideration in all employee plan and exempt organization cases, and in all partnership and S corporation cases.

Preparing the Protest

The taxpayer’s first step in going to Appeals is preparing a protest requesting an Appeals conference.  The protest is a written document which sets forth the taxpayer position.  The taxpayer must file the protest within the 30‑day period required in the IRS’s letter summarizing the Revenue Agent’s findings or advising of other action that gives the taxpayer the right to request an appeal.

The taxpayer may request, and the IRS usually grants, a 30‑day extension to prepare the protest.  If a taxpayer does not retain a representative until after the time for filing the protest has expired, the taxpayer’s representative should go ahead and file a protest.  There is always the possibility that the IRS will accept and process the protest and give the taxpayer an Appeals conference.  Although there is no official form for protests, the protest must contain the following information:

  1. Name and Address – list your name, current address, and phone number.
  2. Statement of Appeal – state that you want to Appeal.
  3. Letter Date and Symbols – place the date and symbol shown on the IRS letter.
  4. Tax Period(s) or Year(s) Involved – state the year or years involved.  List only the year(s) or tax period(s) covered by the appeal which is found on the Revenue Agent’s report of income tax changes.
  5. Itemized Schedule of Tax Changes – This should correspond to the Revenue Agent’s report of income tax changes.  The taxpayer(s) should list the items he disagrees with and the years in which the adjustments appear.
  6. Statement of Facts – The statement of facts section is very important.  In this section, the taxpayer should individually address each item in the itemized schedule that he disagrees with.  The taxpayer should state the facts and the reasons why these items were included on the tax return.  For penalties, the taxpayer should explain why he disagrees with the Revenue Agent.  It is not sufficient to state, at the time of the Appeals conference I will present my facts. The Appeals Officer should be able to make a preliminary determination based on a combination of the taxpayer’s explanation of the statement of facts and the Revenue Agent report.  This should save time in reaching a final resolution of the taxpayer’s case.
  7. Statement of Law or Authority – The taxpayer should state the law and authority that supports his position and include the IRS Code sections, Revenue Rulings, Publications, or court cases that substantiate his position.  If the taxpayer chooses, he can incorporate the statements of law or authority into each item under the statement of facts fact instead of making a separate section.
  8. Perjury Statement – The perjury statement is mandatory, and the taxpayer must sign it.  The exact wording the taxpayer should use is:Under the penalties of perjury, I declare that I have examined the statement of facts presented in the protest and in any accompanying schedules and, to the best of my knowledge and belief, it is true, correct, and complete.If a representative submits the protest, he or she may substitute a declaration stating that he or she prepared the protest and accompanying documents, and whether he or she knows personally that the statement of fact(s) contained in the protest and accompanying documents are true and correct.
  9. Signatures Required for a Written Protest – If the protest relates to a jointly filed return, both the husband and wife must sign the protest.  If the protest relates to a corporation, the corporation’s name should be followed by the signature and title of the officer authorized to sign for the corporation.  A Power of Attorney may also sign the protest.

There are different views as to how detailed a protest should be either it can be very skeletal or very detailed. Experience shows that it is usually better to have a detailed protest setting forth the facts and the law that support the taxpayer’s position.

The protest should set forth why the taxpayer should prevail, and should be written in positive language and not to attack the IRS employee or rebut the IRS’s allegations.  Attacking the IRS or trying to rebut the IRSs position will place the taxpayer on the defense and show a weakness in the taxpayer’s case.  The taxpayer should never pass up the opportunity to go to Appeals.

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/32qveXI
via Abogado Aly Website

Discharging Taxes in Bankruptcy – United States v. Helton

Originally published by Gregory Mitchell.

The recent case of United States v. Helton, Case No. 20-5686 (6th Cir., 2021) addresses the dischargeability of taxes under 11 U.S.C. § 523(a)(1)(C).  The dischargeability of taxes is a somewhat complicated maze of Bankruptcy Code provisions that requires a little bit of analysis.

The Code starts with a general rule that taxes are not dischargeable.  See 11 U.S.C. § 523(a)(1).

However, taxes may be dischargeable if three tests can be met.  Those tests are summarized as follows:

  1. The 3-year test;
  2. The 2-year test; and
  3. The 240-day test.

3-year test

The 3-year test is found in Bankruptcy Code § 523(a)(1)(B), which works in conjunction with § 507(a)(8)(A)(i).  Section 523 is the general “Exceptions to discharge” statute in the Bankruptcy Code, and § 523(a)(1) describes the very first exception to be that of a tax “of the kind and for the periods specified in section 507(a)(3) or 507(a)(8).  Turning to § 507(a)(8), we see the kind of taxes deemed to be nondischargeable as those “for which a return, if required, is last due, including extensions, after three years before the date of the filing of the petition.”

Therefore, we see that taxes are generally only eligible or a discharge after they are more than three years old.  That 3 years is determined from the time when the tax return for the year in question is last due up to

the date that a debtor files for bankruptcy.  So, for example, assuming a 2018 tax return is due on April 15, 2019, that 2018 tax liability becomes eligible for discharge only after April 15, 2022.  Note that it is irrelevant for purposes of the 3-year rule when the return was actually filed.  What matters is when the return was due.  For purposes of the three-year rule, it is also irrelevant whether a payment was made – something that we will see did in fact make a difference in this case.

2-year test

Next, we have a 2-year rule.  Unlike the 3-year rule, the 2-year rule specifically focuses on when the return is filed.  The tax return that generated the income tax debt must have been filed at least two years prior to the filing of your bankruptcy

petition to be eligible for discharge.

It follows, therefore, that failure to file a tax return will prevent a discharge of those taxes in a bankruptcy case.  Note also that, if the IRS files a tax return on behalf of a taxpayer – a substitute for return under Section 6020 of the Internal Revenue Code – a debtor also won’t be able to discharge those taxes.  Reason being, a substitute for return is not considered a return for purposes of discharge in bankruptcy.

So, whether or not a debtor satisfies the 3‐year rule – in other words, EVEN IF a tax is old enough – he or she cannot receive a discharge of taxes if they haven’t filed the relevant return before the date that is two years prior to the filing of the case.

240-day rule

The last of the three tests, the 240-day rule, relates to taxes that have been assessed by the IRS and how long it’s been since that assessment occurred.

If the IRS assessed the tax by an audit, that assessment must have occurred at least 240 days prior to filing the bankruptcy petition in order for that to be dischargeable.

So, even if a debtor’s taxes are for years that are more than three years ago; and even if the debtor filed her return more than two years ago, if the IRS assessed taxes against you last week (or any time less than 240 days prior to filing for bankruptcy),  then that additional amount assessed will not be dischargeable.

In this case, Mr. Helton satisfied all three of these tests.  The analysis focused on an additional provision in the text of  § 523(a)(1), and that is sub-paragraph (C).  Section 523(a)(1)(C) provides an additional barrier to discharge, stating that a discharge may not be obtained for a tax “(C) with respect to which the debtor made a fraudulent return or willfully attempted in any manner to evade or defeat such tax.”

Application

In this case, Mr. Helton has been a self-employed attorney practicing law since 1994. His income fluctuated over the years, approaching $100,000 in the late 1990s but spiking to $178,913 in 2004, $250,536 in 2005, and $234,359 in 2006, before declining to about $60,000 in 2007. But Helton failed to make any estimated tax payments for those years, and did not even file tax returns for years 2004- 06 until several years later. And even after Helton filed his returns, he made minimal payments toward his tax debts for those years and (later) for the years 2009 and 2012.

Meanwhile, Helton enjoyed a comfortable lifestyle, driving a Mercedes-Benz sedan, purchasing numerous luxury gifts for his wife, eating at restaurants “almost every day,” enjoying annual vacations, and spending (along with his wife) an average of $10,000 per month on discretionary purchases during some of the years at issue. Helton also donated about $34,000 to charity during the years in which he failed to pay his taxes, and in 2014 spent an unspecified sum in support of his successful campaign to become a part-time state-court judge.

The United States brought this suit in February 2017, seeking to reduce to judgment its assessments against Helton for the years 2004-07, 2009, and 2012, among other requested relief. Helton filed for bankruptcy two months later. The district court then stayed the case until October 2017, when the bankruptcy court entered an order generally discharging Helton’s debts, thereby lifting the stay.

The sole issue in the case here is whether Helton’s tax debts were nondischargeable under 11 U.S.C. § 523(a)(1)(C).  The district court held a bench trial after which it found that Helton had done precisely that for the years 2004-07, 2009, and 2012. The district court thereafter entered judgment in favor of the United States in the amount of $347,479 for Helton’s unpaid taxes during those years.

The debtor appealed the decision to the Sixth Circuit, which reviewed the district courts factual findings for clear error and its interpretation of § 523(a)(1)(C) de novo.   Looking at relevant Sixth Circuit caselaw, the Court started with the proposition that § 523(a)(1)(C) has both a “conduct requirement” and a “mental state requirement” (citing In re Gardner, 360 F.3d 551, 558 (6th Cir. 2004)). The conduct requirement is met if the government proves that the taxpayer engaged in “acts of omission” or “acts of commission” that themselves amounted to an attempt to evade paying taxes.  Here, Helton does not dispute the district court’s finding that his failure to file tax returns and to pay most of his taxes owed for the relevant years satisfied the conduct requirement of § 523(a)(1)(C).

That leaves the mental-state requirement, which is met if the government proves that the taxpayer “(1) had a duty to pay taxes; (2) knew he had such a duty; and (3) voluntarily and intentionally violated that duty.” Id. at 558.  Helton concedes that he knew he had a duty to pay taxes for the years at issue here, which left only the question whether he voluntarily and intentionally violated that duty. That element is met when the taxpayer has “the financial means to meet his outstanding tax liabilities” but makes “a conscious decision not to apply” those monies “toward his tax debt.” Id.at 560-61.

Here, Helton’s discretionary spending—lavish when compared to the pittance he allocated toward his taxes—amply supported the district court’s finding that Helton’s violation of his duty to pay taxes was voluntary and intentional. See Gardner at 561; compare U.S. v. Storey, 640 F.3d 739, 745 (6th Cir. 2011) (holding this element was not met because “there is no evidence that Storey lived lavishly during the years she did not pay her taxes, or that she chose to engage in recreational or philanthropic activities instead of paying her taxes”).  Helton barely disputes that finding, asserting that he was too busy with work or too depressed during some of the years at issue to pay his taxes. The Sixth Circuit found that the district court did not clearly err when it found those excuses belied by Helton’s ability to maintain his law practice and to run successfully for election as a state-court judge.

Helton’s principal argument, rather, is that § 523(a)(1)(C) requires proof that the debtor acted with “specific intent to evade the tax.” Hawkins v. Franchise Tax Bd., 769 F.3d 662, 670 (9th Cir. 2014). Thus, in Helton’s view, the government was required to prove not only that Helton chose to allocate his funds toward Mercedes-Benz sedans and dinners out each night and luxury gifts, rather than towards his taxes; instead, the government was required also to prove that he purchased or paid for those things specifically to avoid paying his taxes.

The Sixth Circuit emphatically determined that this argument failed and was not the law in the Sixth Circuit, citing to Gardner.  Therefore, the Sixth Circuit upheld the finding of non-dischargeability under 11 U.S.C. 523(a)(1)(C).

The takeaway from this case is that simply satisfying the three normal rules related to dischargeability (as described above) may not be enough.  Where none of the three rules noted above requires any specific level of payment towards a debtor’s tax liability, this case shows that a debtor’s intentional failure to make efforts to pay taxes when the ability to do so exists may invoke the provisions of § 523(a)(1)(C) to result in non-dischargeability despite otherwise satisfying the applicable rules.

The post Discharging Taxes in Bankruptcy – United States v. Helton appeared first on Freeman Law.

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/3gnpM07
via Abogado Aly Website
Texas Legislature to Consider Oil and Gas Lien Law Amendment

Originally published by Charles Sartain.

Co-author Brittany Blakey

Texas lien law in some cases does not require the filing of a financing statement for priority perfection. However, as you might have learned in In re First River Energy, the Delaware Uniform Commercial Code did not recognize the priority of Texas producers’ unfiled, unperfected security interests in proceeds under Texas Business and Commerce Code Section 9.343. In contrast, Oklahoma Producers prevailed because the Oklahoma Lien Act in 2010 cured a defect still present in the Texas statute. Texas producers with a lien are subject to UCC choice-of-law, priority, and perfection of security interests rules.

Rep. Charlie Green introduced House Bill No. 3794 which, if passed, would replace Section 9.343 with the “Texas First Purchaser Lien Act.”

The Bill would remedy the defect by granting Texas working interest owners an oil and gas real property lien rather than a personal property security interest “to the extent of the interest owner’s interest in oil and gas rights” to “secure the obligations of a first purchaser to pay the sales price[.]” The lien would exist as part of and incident to the ownership of oil and gas rights.

A lien would be perfected automatically without the need to file a financing statement (as it is in current Section 9.343), and would “[take] priority over any other lien [except for a permitted lien], whether arising by contract, law, equity, or otherwise, or any security interest.” The Act would replace the 9.343 security interest against personal property (and governed by the Texas UCC) with a real property lien in certain oil and gas rights.

Until the Bill is passed Texas producers who do not file a financing statement (even though Section 9.343 does not require one for automatic perfection), could be in the same losing position as those unfortunates in First River.

Your musical interlude.

Coming soon: Other proposed Texas legislation.

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/3mYUw8W
via Abogado Aly Website

Santos Vargas selected chair-elect of the State Bar Board of Directors

Originally published by Amy Starnes.

San Antonio lawyer Santos Vargas was selected chair-elect of the State Bar of Texas Board of Directors during the board’s quarterly meeting held April 16.

Vargas, a shareholder at Davis & Santos in San Antonio, will take office in June and will serve as chair until June 2022.

Vargas has served on the State Bar Board of Directors since 2019. He served as 2018-2019 president of the San Antonio Bar Association and is a past-president of the San Antonio Young Lawyers Association. Vargas also served as a member and eventually chair of the State Bar Local Bar Services Committee from 2012 to 2019, and sat on the State Bar Annual Meeting Committee in 2015. He is a Fellow of the Texas Bar Foundation and San Antonio Bar Foundation and a member of the William S. Sessions American Inn of Court.

“As the son of immigrants who never had an opportunity to obtain an education in their home country, I am incredibly grateful for the opportunities this country has provided me,” Vargas wrote in his nomination letter to the board. “I have consistently strived to give back through service, including to the legal profession.”

Vargas earned his J.D. from Syracuse University in 2004.

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/3gkrQpD
via Abogado Aly Website