Monday, November 5, 2018

Non-Compete Agreements: Garbage In, Garbage Out

Originally published by Leiza Dolghih.

Enforcing Non-Compete Agreements in TexasLast week, a Texas Court of Appeals ruled that a non-compete agreement between a transportation logistics broker and its freight carrier was unreasonable because it was not clear when the 24-month non-compete period would begin to run. This case serves as a reminder that a confusing, ambiguous, or imprecise non-compete agreement will yield poor results in court.  In other words: garbage in, garbage out. 

The covenant not to compete at issue was meant to ensure that the freight carrier would not take away the broker’s clients after the broker had revealed their identity to the carrier.  Thus, there was a legitimate business reason for the non-compete agreement.  However, the following language in the non-compete agreement created a problem. 

For a period of twenty four (24) months following the Carrier’s last contact with any client or client[s] of Broker the Carrier agrees it shall not either directly or indirectly influence or attempt to influence customers or clients of Broker (or any of its present or future subsidiaries or affiliates) for whom the Carrier has rendered services pursuant to this Agreement to divert their business to the Carrier or any individual, partnership, firm, corporation or other entity then in competition or planning to be in competition in the future with the business of Broker or any subsidiary or affiliate of Broker. 

The Court explained that there were two problems with this language that made it impossible to determine how long the restrictive covenant was going to last.  First, under the terms of the covenant not to compete, the 24-month restraint period would start from the date of the carrier’s last contact with “any” client of the broker, not just the clients that the carrier had provided services to.  Since the broker testified that its client list was a trade secret, the carrier would have no way of determining the date of its last contact with the clients whose identity it had no way of knowing.  Second, the non-compete would begin to run from the date of the last contact, regardless of whether the contact took place during or after the broker-carrier agreement had terminated, which meant that it could begin at any time. 

Consequently, the Court ruled that a covenant not to compete that extended for an indeterminable amount of time was not reasonable, and as a result, was not enforceable. It reversed the jury’s finding that the agreement had been breached and took away the damages the jury had awarded to the broker.

BOTTOM LINE:  There are plenty of “sample” non-compete agreement “forms” online, but there is a difference between a non-compete clause and a non-compete clause that is enforceable. Unfortunately, many companies do not find that out until they are in court trying to enforce their agreements that may not be enforceable.  Companies should avoid using “standard” non-compete clauses and make sure that their restraints are tightly drafted to address their specific industry, business model, and particular needs. 

Leiza litigates trade secrets and non-compete agreements disputes in a variety of industries.  If you are a party to a dispute involving a non-compete agreement or theft of confidential information, contact Leiza at Leiza.Dolghih@lewisbrisbois.com or (214) 722-7108 or fill out the form below.


[contact-form-7]

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/2PDJaci
via Abogado Aly Website

Appellate jurisdiction sails away in coverage dispute

Originally published by David Coale.

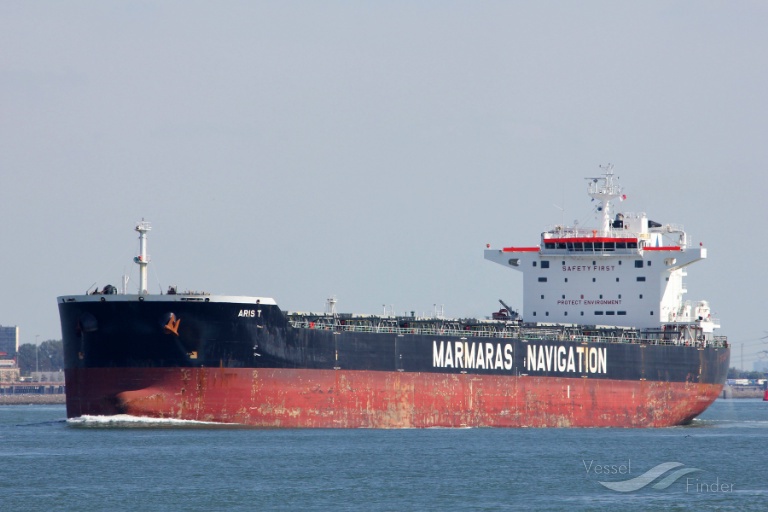
The issue in SCF Waxler Marine LLC v. Aris T MV was whether the excess insurers for a multi-vessel accident could enforce a “Crown Zellerbach clause,” and thus limit their liability to the value of the insured vessel. (The vessel at issue, the Aris T (right) is presently in the Atlantic en route to Rotterdam from Mobile.) The Fifth Circuit found that it lacked appellate jurisdiction over the district court’s ruling that the excess insurers could enforce such a clause: “The fundamentals of Bucher-Guyer bear a striking resemblance to this case. There, the district court determined the boundaries of a party’s liability— $500—based on the applicability of statutory language. Nevertheless, whether the opposing party was entitled to anything and, if so, how much was still to be determined. In this case, the court decided the boundaries of a party’s liability through determination of whether a contractual provision permitted them to do so. Whether Valero, Shell, and Motiva are legally permitted to recover anything from the Excess Insurers and, if so, how much remains to be determined.” No. 17-30805 (Oct. 30, 2018).

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/2RB7hp4
via Abogado Aly Website

Determining the Reasonableness of Medical Charges – The Quest Continues

Originally published by Sarah Scott.

Texas Supreme Court Rules Government and Insurance Billing Rates are Discoverable for Determining “Reasonableness” of Hospital Charges to Individuals

One of the biggest factors affecting the value of a personal-injury case is the amount of medical bills – hospital bills, in particular. To encourage hospitals to promptly and adequately treat accident victims who are uninsured, the Texas Legislature has granted hospitals a lien on any patient injured in “an accident that is attributed to the negligence of another person.” Tex. Prop. Code §55.002(a). These liens – which attach to any settlements or verdicts arising from these accidents – are “subject only to the right to question the reasonableness of the charges.” Bashara v. Baptist Mem’l Hosp. Sys., 685 S.W.2d 307, 309 (Tex. 1985).

With medical billing, however, “reasonableness” is not exactly straightforward. Most hospitals have a tiered charging system for their patients; those patients covered by Medicare or private insurance benefit from the collective bargaining power of the government or insurers and are charged less for medical services. Individuals not covered by insurance, on the other hand, are subjected to (often astronomically high) “chargemaster” or “list” rates. Often, hospitals end up writing off a substantial portion of these higher charges for uninsured patients who will realistically never be able to pay them.

So what happens when a hospital learns of a lawsuit where insurance is involved and refuses to reduce the amounts it charges to a plaintiff?  That was the issue facing the Texas Supreme Court in In re North Cypress Medical Center Operating Co., Ltd. No. 16-0851, 2018 WL 1974376 (Tex. April 27, 2018). Crystal Roberts was involved in an auto accident and taken to the emergency room at North Cypress Medical Center. After receiving X-rays, CT scans, and labs, she was released after three hours. Id. at *1. Since Roberts was uninsured, she was billed at the chargemaster rates, which totaled $11,037.35. Id. Roberts’ attorney tried to reduce the amount of the lien to settle the case with the at-fault driver’s insurance company; when the hospital refused to reduce the bill below $8,278.31, Roberts sued the hospital. In discovery, he asked for the hospital’s billing rates for the same services for patients who had Medicare or private insurance.

The trial court granted Roberts this discovery, and North Cypress filed a petition for a writ of mandamus. Id.at *2. North Cypress argued that information on pricing for Medicare and private insurance was not relevant to whether its pricing for uninsured individuals was reasonable. The Texas Supreme Court noted that the chargemaster prices have no connection to the prices a hospital actually expects to receive for its services – instead, the chargemaster prices are high and continuing to increase, since the higher list prices translate to higher reimbursement rates for Medicare and Medicaid. “[B]ecause of the way chargemaster pricing has evolved, the charges themselves are not dispositive of what is reasonable, irrespective of whether the patient being charged has insurance…. We fail to see how the amounts a hospital accepts as payment from most of its patients are wholly irrelevant to the reasonableness of its charges to other patients for the same services.” Id. at *4.  After noting that courts in multiple other jurisdictions had held similarly, the court denied North Cypress’ petition for mandamus and allowed the trial court order to stand.

Until North Cypress, plaintiffs had little ammunition against hospitals who sought to recover inflated liens on charges to uninsured patients. The big question now is whether defendants can take advantage of this ruling to exert pressure on plaintiffs seeking unreasonable fees to take a more realistic approach to settlements – but that, no doubt, will be the subject of future litigation.

The post Determining the Reasonableness of Medical Charges – The Quest Continues appeared first on Hanna Plaut.

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/2PIOmLG
via Abogado Aly Website

Friday, November 2, 2018

Top 10 from Texas Bar Today: Prince, Inception, and Stranger Things

Originally published by Joanna Herzik.

To highlight some of the posts that stand out from the crowd, the editors of Texas Bar Today have created a list from the week’s blog posts of the top ten based on subject matter, writing style, headline, and imagery. We hope you enjoy this installment.
10. Texas Couple Indicted for Allegedly Embezzling $14.5M from Retirement Funds @SSEKLaw in Houston

9. Prince’s Estate Wants to Trademark the Color PurpleGerry Beyer @Gerry_Beyer, Law Professor at Texas Tech University School of Law in Lubbock

8. Time for Hot Chocolate and Completed Outlines – Steven Foster of Law School Academic Support Blog

7. Protecting Your Store’s “Look” With a Design PatentThe Kumar Law Firm PLLC in Austin

6. Chen’s Noodle House – Rediscovering a Hidden Gem – Michelle Cheng of Whitehurst Harkness Brees Cheng Alsaffar & Higginbotham PLLC @NatlTrialLaw in Austin

5. 202 and immunity, oh my.David Coale @600camp of Lynn Pinker Cox & Hurst, LLP in Dallas

4. An Employer’s Spooky Interpretation of its Bring Your Own Device (BYOD) PolicyDrew York of Gray Reed & McGraw @GrayReedLaw in Dallas and Houston

3. A Burden Shift within A Burden Shift—An Anti-SLAPP ‘Inception’Daniel Correa of Creedon PLLC @CreedonPllc in Frisco

2. LinkedIn is Boring – But Lawyers Should Be There AnywayAmy Boardman Hunt of Muse Communications, LLC @MuseCommLLC

1. Stranger Things, IndeedJohn G. Browning @therealjohnbrow of Passman & Jones in Dallas

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/2yKQ060
via Abogado Aly Website

Court Finds ERISA Requires Disclosure of “Reasonable and Customary” Methodology

Originally published by Haynes and Boone Benefits Group.

A federal district court in Michigan, in Zack v. McLaren Health Advantage, Inc., recently considered whether the claims regulations under ERISA require an employer-sponsored group health plan to disclose its methodology for determining the “reasonable and customary” amount related to a benefit claim for services rendered to a plan participant by an out-of-network medical service provider, regardless of whether the participant requested such information.

Summary of the Case

The claimant, Zack, who was a participant in the group health plan sponsored by her husband’s employer, obtained medical services from an out-of-network provider and filed a benefits claim under the plan. The plan stated that out-of-network benefits would be paid at 60 percent of a “reasonable and customary amount”, but did not define what that term meant or how it would be calculated. In practice, the “reasonable and customary amount” under the plan (“R&C Amount”) was determined by calculating an average derived from various fees charged by the plan’s in-network providers for the same kind of procedure (the “Methodology”).

The plan sponsor was the plan’s claims and appeal decision maker in this case and determined that Zack’s claim would be paid at 60 percent of the R&C Amount as calculated based on the Methodology; however, the plan sponsor did not disclose the Methodology in its claim determination notice to Zack. Zack then challenged the plan sponsor’s calculation of the R&C Amount on appeal under the plan. The plan sponsor upheld its original decision on the claim but did not directly address Zack’s challenge regarding the R&C Amount or disclose the Methodology in its appeal determination notice sent to Zack. Thereafter, Zack filed suit against the plan sponsor.

The court noted that Zack never requested a description of the Methodology from the plan sponsor but, even so, held that where a plan participant specifically challenges the calculation of the R&C Amount for reimbursement, ERISA requires disclosure of the methodology applied as part of the plan sponsor benefit and appeal denial in order to provide a “full and fair review” of the claim as mandated by ERISA.

The court further found that because the plan failed to provide a definition of the R&C Amount, and also offered no explanation of the meaning of this term during the benefit or appeal process, the plan sponsor’s denial of the benefit claim on appeal based on its undisclosed interpretation was “arbitrary and capricious” under ERISA’s standards. The court remanded the benefits claim back to the plan sponsor, ordering that the plain meaning of the term “reasonable and customary amount” (i.e., the prevailing market rate generally charged for the service in the relevant geographic area) be used by the plan sponsor in performing a full and fair review of Zack’s claim.

Practice Tips for Group Health Plan Sponsors

Zack is controlling only in the jurisdiction of the federal district court in Michigan that issued the opinion. However, this case highlights several general tips that group health plan sponsors should consider:

  • Plan documents and summary plan descriptions should be carefully reviewed and revised as needed to ensure that key terms, such as “reasonable and customary amount”, “allowable amount”, and similar terms that determine the basis for benefit payments are clearly and accurately defined (including, as appropriate, references to any applicable methodologies).
  • The plan sponsor should confirm that any third-party claims administrator is processing claims in a reasonable manner and using methodologies that are consistent with the terms of the official plan document and summary plan description (including definitions of key terms).
  • The plan sponsor should confirm that the plan’s decision maker is issuing claim determination notifications that contain the information required by ERISA’s claims review and appeal regulations (including, as appropriate, any methodologies, internal guidelines, or similar criteria that were relied upon by the decision maker in making the claim or appeal determination).

Zack v. McLaren Health Advantage, Inc., No. 17-11253 (E.D. Mich. Sept. 20, 2018).

The post Court Finds ERISA Requires Disclosure of “Reasonable and Customary” Methodology appeared first on Haynes and Boone Blogs.

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/2OiM41i
via Abogado Aly Website

Plaintiffs Lawyers Fight to Keep $4.7B Talc Verdict, Citing J&J’s ‘Perfect Storm’ of Misconduct

Originally published by Amanda Bronstad.


Johnson & Johnson has filed motions to toss the verdict, accusing plaintiffs’ lawyer Mark Lanier of referencing stillborn babies in his opening statement and showing a drawing of a woman pushed over a ledge into ovarian cancer.
      

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/2P30mbq
via Abogado Aly Website

Savings on retail products

Originally published by Staff Report.

Your Member Benefit Program has incredible offers from fun, new brands and long-time favorites. Visit the Electronics, Retail, and Home & Garden pages to start saving.

  • HP Employee Purchase Program — HP is where power meets performance. Save on laptops, desktops, tablets, and more with exclusive pricing and instant rebates.
  • Vitamix — Thanks to the Vitamix Employee Discount Program, you can enjoy exclusive savings on Vitamix blenders. Receive 15% off any Vitamix blender, container, or accessory.
  • Rollick — At Rollick Powersports, you can experience the thrills and excitement of off-road adventures without a shopping struggle. Customers save an average of $1,130.
  • Harry & David — Since 1934, Harry & David has grown to become America’s premier choice for gourmet gifts. State Bar of Texas members receive 15% off fresh fruit and other delicious gifts.
  • Sunski Sunglasses — Sunski shades are always polarized, light-years from ordinary, and backed by a forever warranty. Take 25% off your order.
  • LifeProof — LifeProof cases and accessories let you take your tech along on your adventures. Take 20% off LifeProof protective cases for your phone or tablet.
  • Lenovo Computers — Looking to upgrade your PC or laptop? Thanks to Lenovo’s Corporate Employee Purchase Program, you can save on the entire product line.

Current offers provided by Beneplace.

For more information on other discounts you’re eligible for as a member of the State Bar of Texas, visit texasbar.com/benefits.

Texas Bar Private Insurance Exchange
The Texas Bar Private Insurance Exchange is a multi-carrier private exchange designed for State Bar of Texas members and their staff and dependents. Available to both individuals and employer groups, the exchange offers a wide range of health insurance choices and more.

State Bar of Texas – Benefits & Services

Curated by Texas Bar Today. Follow us on Twitter @texasbartoday.


from Texas Bar Today https://ift.tt/2CWtcTE
via Abogado Aly Website